

Build Guarantee
Price Lock Guarantee
Contract Guarantee
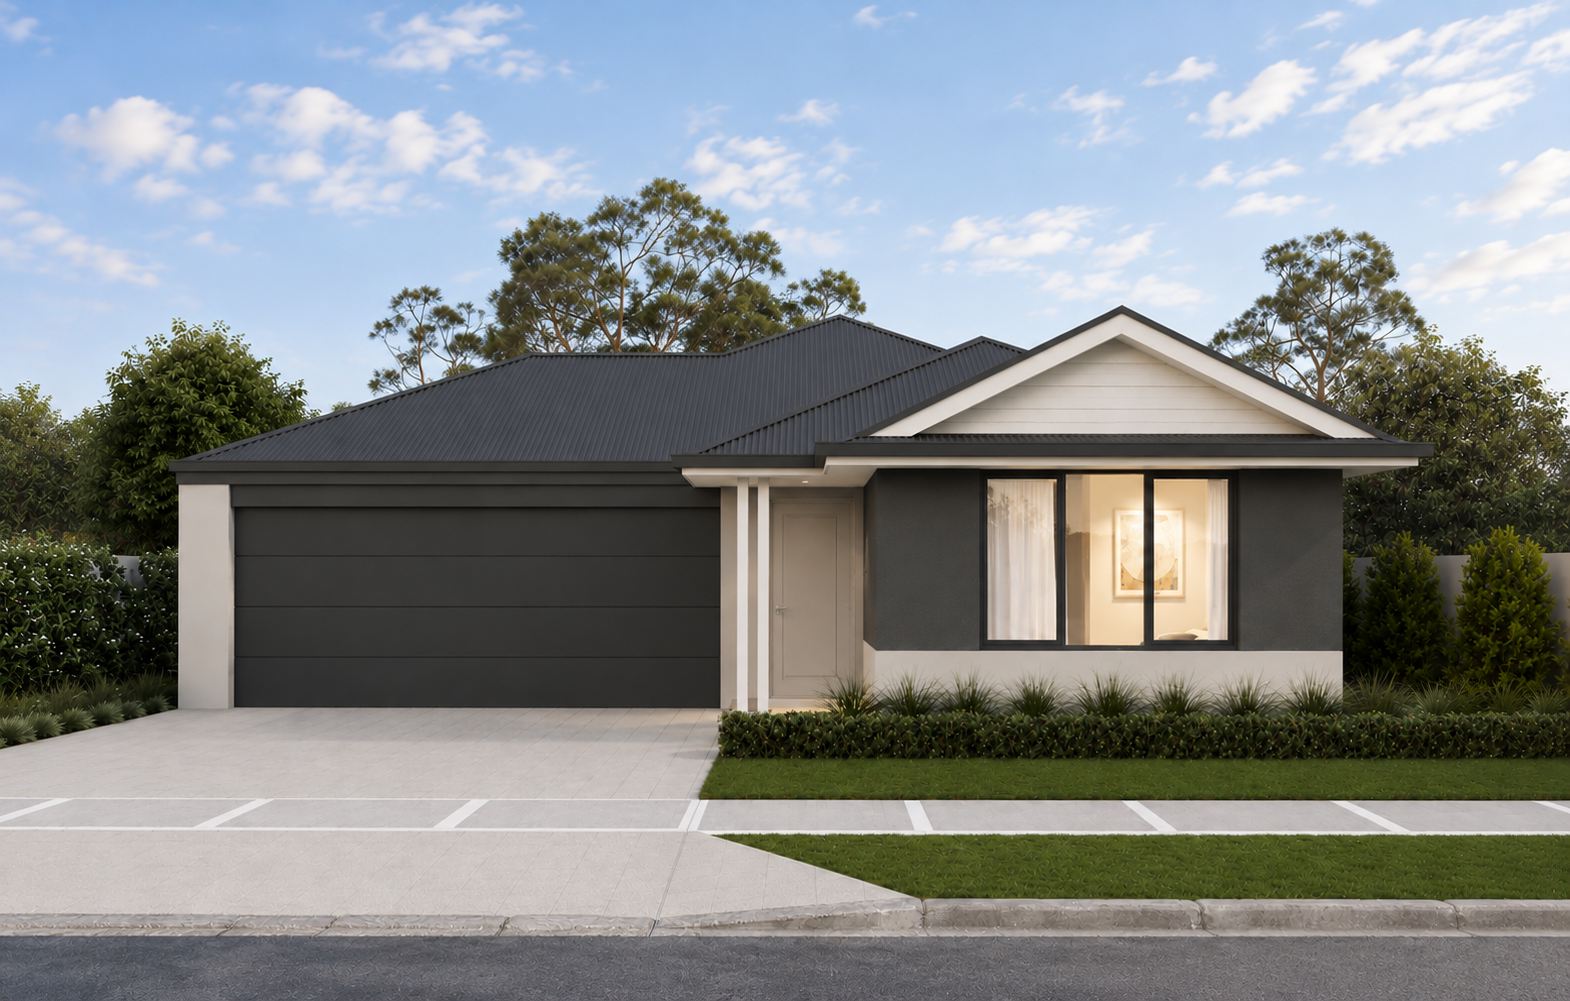
FROM $397,790*
 4
 2
 2
 15M
 227M2
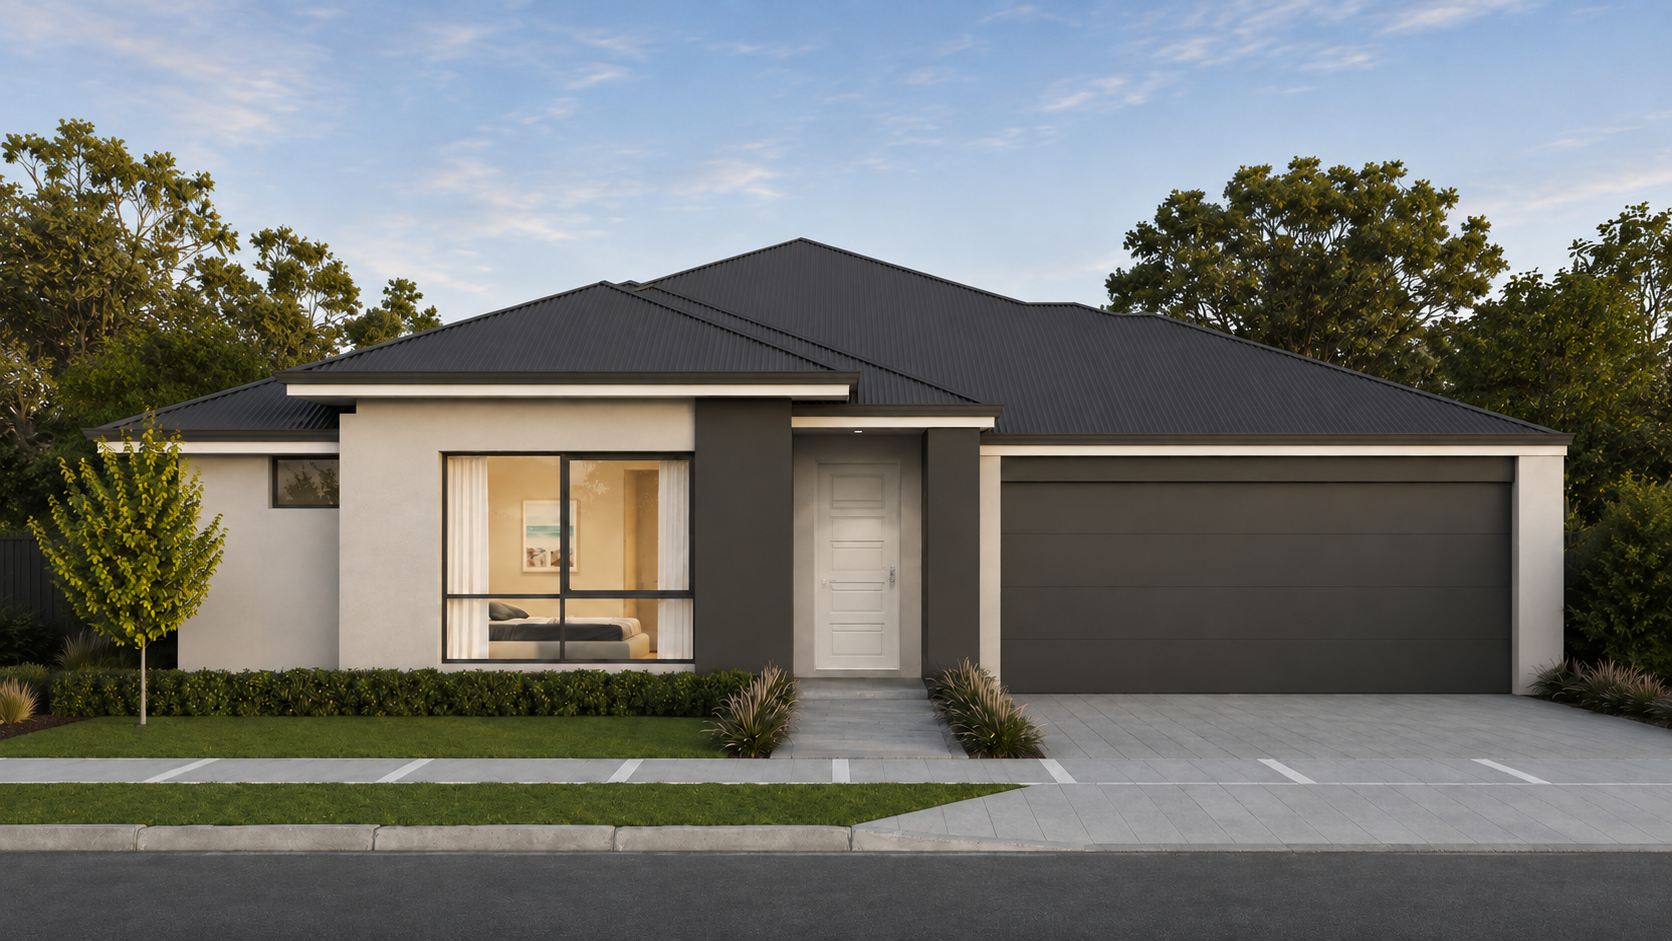
FROM $363,590*
4
2
2
15M
193M2


FROM $368,290*
4
2
2
12M
195M2

FROM $360,290*
4
2
2
12M
187M2
FROM $342,990*
3
2
2
15M
164M2
A shortcut to finding your perfect home design. Or skip this step and go straight to the design you’ve been eyeing.
You’ve been visualising it, pinning it, manifesting it; and now you can design it. But you don’t have to do it alone, we’re the ones who are here when you need us.
Making your mark starts with your money. Head to our finance page for grants you might be sitting on, borrowing calculators, and everything else to turn the plan into real numbers.


Without the heavy layers of big-builder bureaucracy, we champion real change. And then give ourselves the mandate to act on it. Starting with a fully certified energy-efficient NCC-compliant home.

There are some things we'll happily leave with big-business builders. Like adding $ behind the scenes then promoting a discount - hot tip: there never was one! With us, what you see is what you get.
This is your home and you're the one who made it happen. Sure, we were part of the team who you assembled, but this is all you. Your home, built by you.
Your new home is already remarkable. But what about the rest? Tell us the kind of new home (and new home experience) you want, and we'll make it happen.


“You guys were just so refreshing, it was very open and honest and fun. Communication was really good, and pretty much everything we asked was answered and addressed. Overall, the experience was really good, everyone was friendly, and we never felt like we were a burden. Our slab went down at the end of January, and we got our keys end of September. It went pretty quickly.”
It’s likely! Depending on where you’re located, Keystart Home Loans (WA) & Homestart Home Loans (SA) are easier to get than ever. Provided you are:
There’s a good chance you’re eligible for a Keystart/Homestart Home Loan. The Debt Servicing Ratio (DSR) requirement was removed a few years ago too, so if you have a car loan, personal loan or credit card which exceeds 10% of your monthly income, you’re still eligible. Now how remarkable is that?!
Being a first-home owner is pretty remarkable all by itself. But it also comes with a completely catch-free, no-strings-attached, never-ever-have-to-repay boost from your state government.
It’s called the First Home Owners Grant (FHOG), and it’s designed to help renters break out of the landlord cycle and step into a brand-new space of their own. In Western Australia, it’s a $10,000 grant. In South Australia, it’s a grant of up to $15,000.
Each state government has clear criteria for who gets the cash. To claim your grant, you and your property must tick these seven boxes:
| Criteria Category | The Exact Rule | The Fine Print |
| Legal status | You must be a real-life human. | No family trusts, companies or corporate entities allowed. |
| Age limit | You must be 18 or older. | If you’re under 18, you have to apply for a special exemption. |
| Residency | At least one applicant must be an Aussie. | Must be an Australian citizen or a permanent resident at the time of application. In SA, eligible New Zealand citizens holding a Special Category visa may also qualify. |
| Property history | You must have never owned a home in Australia. | If you’ve owned property anywhere in Oz before, your eligibility might be affected. The exact rules vary between WA and SA. |
| The partner | Your spouse or de facto must also be a first-timer. | If your partner received the FHOG or owned a home before, you can’t claim it as a couple. |
| The price cap | The rules depend on where you’re building. | In WA, your house and land package must be under $800,000 in metropolitan areas (like these). In SA, there’s currently no property value cap for eligible contracts entered into on or after the 6th of June 2024. |
| Move-in timeline | You must live in the home for at least 6 continuous months. | You have to move in within 12 months of handover and stay for at least half a year. |
Let’s bust a common misconception: the government doesn’t drop a couple of grand into your bank account the day you sign your contract so you can go on a shopping spree at IKEA.
Although we wish that were the case, since you’re building a new home, the application is lodged through your construction lender.
RevenueWA releases the $10,000 directly to the bank at the slab down stage (when the foundations of your house are poured). This money acts like a massive equity injection, lowering the overall amount you need to draw down on your loan.
In SA, it works a little differently. The grant is generally paid through your lender or approved agent at the first progress payment stage of the build. Just like in WA, it helps reduce the amount of funding needed throughout construction, making the journey to home ownership that little bit easier.
If you qualify for the FHOG, the savings get even better. The government scales back your transfer duty (stamp duty) via the First Home Owner Rate.
For a house and land package, you only pay stamp duty on the land component. In WA, first home buyers now pay no stamp duty on vacant land up to $450,000, with reduced rates up to $550,000. For homes, no duty is payable up to $600,000, with concessions available up to $800,000.
In South Australia, stamp duty relief is available for eligible first home buyers, and for contracts entered into on or after the 6th of June 2024, no property value cap applies to eligible new homes and vacant land used to build a home.
Compared to buying an established home, where you pay full tax on the whole purchase price? Building new saves you tens of thousands.
Figuring out loan structures, land titles and government forms can feel like trying to solve a Rubik’s Cube blindfolded. That’s what we’re here for. We handle the heavy lifting, boring paperwork and everything in between.
If you’re ready to stop paying your landlord’s mortgage and start building your own equity, let’s chat.
Is the thought of paying your mortgage AND rent at the same time giving you the sweats? What if we said you didn’t have to?
Meet: construction loans. Unlike traditional home loans, construction loans allow you to lend in stages rather than in one single (expensive) lump. It means you pay the smallest amount possible while your new home is built.
You’ll save thousands while you build, free up your finances for rent – or new furniture, fun! – and lift a whole lot of financial pressure off yourself.
Not sure where to start? Our finance brokers can help you break down what your future weekly repayments would be throughout construction, to ensure you’re comfortable and able to afford them.
Unlike traditional home loans, Construction Finance allows you to lend in stages rather than in one single (expensive) lump. It means you pay the smallest amount possible while your new home is being built.
With construction loans, as your new home progresses, so do your payments. They’re called ‘progress payments’ (funny that) and they’re charged as key construction milestones are reached. Like:
Then, only when your home is officially move-in ready (yay!), your loan will start to work like any other home loan. Thank you, Construction Finance.
A little word of warning: Construction Loans are very different from regular home loans, both in terms of how they are set up and their application, and only account for 8% of the total loans in Australia.
So, unless you’re aware of all the differences and confident in their application, we suggest getting some advice from a specialised mortgage broker, like those at Oui Finance, who are experts in this space. In fact, even if you do consider yourself something of a lending legend… just go ahead and get the advice anyway.
Before we get lost in the $$$, let’s break it down. Stamp duty (aka transfer duty) is basically a “welcome to the neighbourhood” tax from the government. It’s calculated based on your property value and where exactly you’re building your vision.
The good news? There are some remarkable savings on offer:
Let’s unpack:
| Vacant Land (part of a house & land package) | Duty Payable | |
| Western Australia | South Australia | |
| $0-$350,000 | No duty payable | No duty payable |
| $350,001-$450,000 | You’ll pay $15.39 for every $100 (or part thereof) above $350,000 | |
| $450,001+ | Standard residential stamp duty rates apply | |
*Details correct as of April 2026
Think of it like a ladder. Instead of one flat rate, the state looks at your purchase price and applies different tax brackets as you climb higher.
The price tag is the big driver here. As the value climbs, you move into higher brackets where a larger percentage is taxed. For house and land packages, the value used is generally the land’s value at the time of signing, not the finished home. This can slash your upfront costs.
Each state decides its own thresholds, rates and concession schemes based on local housing conditions.
That’s why a buyer in WA might pay a completely different amount to someone in SA for a similar property, and why your budget needs to be 100% local. What works in Perth might look totally different in Adelaide.
Concessions are designed to help you get into the market without the massive headaches. These perks tend to favour new builds or vacant land. The way house and land purchases are structured makes it much easier to score these savings.
The answer? Sometimes yes, sometimes no. It all depends on your eligibility, the type of property you’re eyeing and the final price tag.
For some, stamp duty gets reduced. For others, it’s completely gone. If your purchase falls outside the criteria, though, you’ll be paying the standard rate like everyone else.
It’s not just an automatic “yes”. You’ve got to be a genuine first-home buyer who hasn’t owned property in Australia before. Plus, the home needs to be your actual residence, not an investment property.
There are also price caps that vary by state. If your price tag sits even a dollar above the threshold, you might lose the exemption or only get a partial discount. Precision is key!
Stamp duty isn’t something you’ve got to worry about the second you make an offer. It comes into play much closer to settlement, when the keys are almost in sight!
When you sign on the dotted line, you’ll pay a deposit first. Stamp duty is a totally separate cost and is typically paid at or just before settlement. Your conveyancer will ensure the funds arrive on time so your move-in date stays on track.
Like we said before, there’s no single “magic number” that applies to everyone. There are a few key factors that decide your total bill:
Building new is much kinder to your bank account. You’re usually only taxed on the land value, whereas buying established means paying duty on the whole property.
First-timers get the perks. If this isn’t your first home, you’ll likely be hit with the standard rates, meaning you’ll need a bit more stashed away before you get started.
Each state plays by its own rules. Because stamp duty works on a sliding scale, knowing your local thresholds is the best way to make sure you’re making your mark without any surprises.
At the end of the day, stamp duty isn’t just another bill. It’s the final hurdle between you and your own front door. While the numbers can feel like a lot to juggle, knowing exactly where you stand with concessions is your biggest advantage. It’s the difference between a budget that actually works and a last-minute scramble.
The best move? Don’t guess the math.
Every situation is a little different, and the state thresholds go down to the dollar. Get your plan locked in early, double-check your eligibility and make sure your budget is set up for success from day one.
You’ve done the hard work; make sure getting over the finish line is smooth too.
Well, technically your first payment is at sign up when you put your deposit down to build.
All builders request a similar amount deposit – usually a couple of grand – all of which goes towards getting your home through preconstruction and ready for site. Think: working drawings, contracts, prestart/selections, personalised portal, interior design consultation, etc. As such, they’re non-refundable.
After your deposit, you will be required to make a pre-construction payment once settlement has occurred and your building permit has been issued. You then won’t be required to make another home loan payment till your build is underway. Progress payments are due within 10 working days and are issued at different stages based on your state:
WA
SA
Any variations made at Prestart/Selections (extra cabinetry we’re looking at you!) need to be paid at or before construction.
Depending on your bank, home loan, and borrowing capacity, your variations will either be funded by your bank (ie, via your loan) or out on your own funds (ie, via cash).
When in doubt, check with your bank or broker.
It’s best to speak with your bank or broker about this one, because the answer varies!
Depending on your bank, your home loan and most importantly, your borrowing capacity, they’ll either suggest you include Variations in your finance or pay for them out of your own funds.
In a way, yes. Because, you (the buyer) know the full cost of your house and land upfront, right down to the siteworks. Meaning there are no unexpected costs in your future from either the builder or the developer. Your New Homes Consultant will haggle on your behalf to ensure you get the best price for the house AND the land, saving you precious time, energy, and money. Speaking of, you’ll only need to pay stamp duty on the value of the vacant land – which will save you a pretty penny too.
Possibly – it all comes down to the price of your land. If your land is valued below $300,000 (which is very possible in Perth’s new estates) you can forget about stamp duty.
However, once the land portion of your package creeps over $300,000, stamp duty becomes payable. The exact cost depends on the price of your land so when in doubt, speak to one of our House and Land experts – they’ll be able to give you a full breakdown of the costs involved. The good news? Regardless of whether you need to pay stamp duty on the land or not, there’s absolutely no stamp duty payable on the home itself.
The good news? Regardless of whether you need to pay stamp duty on the land or not, there’s absolutely no stamp duty payable on the home itself.
A house-and-land package is one of the most popular ways to build a new home in Australia.
In a nutshell, it’s a block of land from a developer paired with a brand-new home from a builder, bundled into one all-inclusive deal.
You can find these ready to go under our ‘House and Land’ tab, but if your perfect match isn’t there, don’t sweat it. We can create one for you entirely from scratch! Our number one rule? There aren’t any!
Choosing a package also makes financing a house-and-land purchase a whole lot easier. Instead of juggling two separate loans for the dirt and the build, you can usually just roll them all into one. It keeps things transparent and saves you from unnecessary fees (which is something we’re very big on here)!
This is where our expert matchmaking comes in. We take a location that’s brimming with life and pair it with a home design that’s a perfect fit for the block’s size and orientation. Because we’ve already done the legwork, making sure the house suits the land, you don’t have to worry about the technical stuff. We’ve taken care of that!
Once the land is secured, the build moves through your typical construction stages. Since it’s a package, we’ve often already checked the council approvals and site requirements for that block before the home is built. From there, it’s about turning those floor plans into a reality, step by step, until the keys are in your hand.
Transparency is a big deal when buying a house. Most packages outline the standard inclusions upfront so you know exactly what’s in the box. This usually covers the design, the building specs and the base price for that specific block of land.
At La Vida, our base price isn’t just a bare-bones start; it’s stacked with all the essentials, so you’re living the good life from day one.
Some features might be classed as upgrades or exclusions, like premium finishes or landscaping. That’s why we stick to a fixed price, so you know exactly where the package ends and where any extras begin. It means you can plan your move without worrying about unexpected costs popping up at the last minute.
Below, we’ve put together a little table so you can get a rough idea of what’s typically included in an average build:
| Inclusions vs Exclusions | |
| Base works (usually included) | The extra bits (often excluded) |
| A specific block of land paired with a house design that fits it | Stamp duty on the land, transfer fees and your solicitor’s bill |
| The full construction of the home, from the slab to the roof | Driveways, paths, fencing and front/back landscaping |
| Your base kitchen, bathroom, floor coverings and light fittings | Any “luxe” upgrades like stone benchtops or high-end appliances |
| Council application fees, building permits and standard insurance | Clotheslines, letterboxes and window treatments (blinds/curtains) |
| Connecting the house to the mains (water, power and sewerage) | Major retaining walls or extra work for blocks with a steep slope |
A construction loan is the standard move here. Instead of paying for the whole build upfront, funds are released in stages as the work happens. It keeps the process manageable because you only draw what’s needed as the build progresses.
Even though you’ll sign different contracts for the land and the house, your lender can usually bundle the financing into one convenient approval. It’s a good idea for buyers who want a clearer path to their dream home without the double paperwork.
Stamp duty concessions can be a massive win for your bank account. Your eligibility criteria depend on your state, but it’s always worth checking if you can pay stamp duty on just the land value rather than the finished house. Knowing what’s available to you lets you budget with total confidence.
There’ll always be a few bits and pieces outside the headline price. Site works, council approvals and service connections all play a part in the final figure. We factor these in from the get-go so you get a full picture of the cost before you make your mark.
For plenty of home buyers, a package is a great move. It cuts out the guesswork and gives you the confidence of knowing your land and your design were made for each other from the start. If you’re after a smoother, more straightforward path to a brand-new home in a suburb you love, this is how you make it happen.
Ready to see what’s possible? Let’s get to work. Get in touch and let’s start building a place that’s 100% you.
A turnkey package makes building a new home as simple as can be, as it’s ‘move in ready’ from the moment you get the keys. Meaning, it comes complete with floor coverings, window treatments, internal wall painting… the lot!
Not all house and land packages are turnkey (the difference between a standard and a turnkey package is approximately $10-$15k) but they can all be turned into one. So if this is a non-negotiable for you, let your New Homes Consultant know and they’ll make it happen.
The First Home Owners Grant (FHOG) is a one-off payment designed to motivate and help first home buyers get into the property market. It’s offered by the government, so its value will depend on the state you’re living in. Here in Western Australia (WA), there’s currently $10,000 big ones on the table.
The grant is ‘genuine’ meaning if you qualify, you’ll never need to pay back the $10,000 and you’ll be eligible for a stamp duty exemption which could save you even more. As you can imagine, the scheme has been incredibly popular since it was launched in 2008, with over 1,000 happy homeowners using it to break into the property market a month. Yes, a month!
As for the big question… do you qualify? The good news is the grant isn’t means-tested, so your income won’t affect your eligibility. However, you do need to meet the following qualifying criteria. You need to:
Sound like you? Ten thousand big ones and a new home could soon be yours. Speak to your New Homes Consultant or Finance Broker for more info.
A turnkey specification takes the guesswork and stress work out of building a new home, because all the fixtures and finishes you need for your new abode to be ‘move in ready’ are included from the get-go. Such as floor coverings, window treatments, and internal wall painting.
La Vida Homes has a range of specifications so you can choose the level of add-ons and inclusions that are right for you. For some, this means going with a complete turnkey finish, while for others it means selecting something a little less ‘done’ – so they can get their hands dirty and add the final flourishes themselves post-handover. Which is just a long and winding way of saying it’s up to you, and your budget!
If you have any questions, just ask your New Homes Consultant about the options available and which one they believe is right for you.
There’s a lot to consider when selecting a block. Its proximity to your favourite watering hole, bestie’s place, and freeway are all key considerations of course, but… what about the block itself? For example, is it flat or sloping? What’s the street appeal like? How about solar orientation? The list goes on.
We recommend narrowing down your search to within 10km of your dream location, then comparing and contrasting the block sizes and prices on a m2 basis. Be sure to take into account any bushfire, noise and site works requirements too (the developer will be able to fill you in on all these when pressed).
Alternately, feel free to lean on your New Homes Consultant. It’s what they’re there for! They can take on all the research, identify what land is available, dig into the costs (like, really dig in), and run you through the options. You’ll still be purchasing the land directly through the developer, so you can trust them to be an informed and objective sounding board more than anything else.
If you’re in Perth, you’re in luck! We build everywhere from the inner suburbs to the popular outer estates and beyond. We even go as far as Two Rocks in the North, Dawesville in the South, Bullsbrook in the North East and Byford in the East.
With land being snapped up faster than ever, most of the time ‘where’ we build comes down to availability. So if there is a slice of WA you’d like to call yours, let us know and we’ll help you get there.
Yes, cracks in concrete slabs are a pretty common occurrence and don’t usually warrant any alarm bells.
The cause of most is simply because concrete shrinks as it loses moisture, when temperature drastically changes, or when there is ground movement.
Small cracks in your slab won’t interfere with the structural integrity of your new home. But in the very rare case, we identify that it could affect your home’s structure, we’ll have it fixed quick smart.
Yes, the weather can impact your build, and not in a good way. Sorry to be the bearer of bad news but you know we like to be straight with you!
Winter and construction don’t really vibe with each other, but that doesn’t mean nothing is going to happen for three months of the year.
All it means is that if your build is in the early stages, our timelines might move around a bit depending on what Mother Nature has in mind. We can’t pour a slab when it’s pouring, brickies can’t put up walls when it’s wet and it’s too dangerous for carpenters to get on the roof if there’s a storm brewing. If we could turn the clouds off for you, we would!
The good news? Once your roof is up and works move inside, you’re golden, rain or shine! Our advice in the meantime? Be good to your Mother, and she might be good to you 😉🤞
A building PCI is the tour you’ve been waiting for.
No, Beyonce isn’t coming to town (but we live in hope 🤞).
It’s a tour of your new home with your superstar site supervisor.
During your Practical Completion Inspection (PCI for shorts), you’ll be walked through every room to make sure every detail is exactly what you want.
Anything that needs to be fixed will be actioned within 10-14 days, then we book in handover! A.k.a., key time, baby!
The lock up stage is a huge milestone in your building journey. Your bricks are bonded, your roof is up, and your windows and doors are in. Basically, your home can be ‘locked up’!
Meaning not only are you halfway through your building journey, but your home is secure and we can send more material deliveries your way.
Now, things start to move inside. Your cabinetry will be installed, your flooring will be laid, your tilers will tile, and the time to handover will fly!
